

Vietnam’s first week as an FTSE Russell secondary emerging market ended with net foreign selling, yet the week’s corporate news pointed the other way. Founders, parent companies and strategic investors moved to settle who controls what, and how much stock the public can buy, before planned listings in 2026 and 2027.
What changed this week
FTSE Russell’s reclassification of Vietnam took effect on 21 September. Portfolio investors did not treat it as a reason to buy. The VN-Index fell 1.68% over the week to 1,785.11 points, according to Vietstock. Tin Nhanh Chứng Khoán (Securities Investment Newspaper) reported that foreign investors were net sellers of nearly VND2.8 trillion across the exchanges, with the selling concentrated in large caps such as Vinhomes (VHM) and VPBank (VPB). The week before, they had been net buyers.
Corporate activity was busier. In seven days the market saw a founder take back majority control of a national consumer brand, a US strategic investor buy into a Vietnamese tungsten producer as its parent prepared to widen free float, a Japanese bank reported to be negotiating a larger stake in a Vietnamese lender, and a Japanese strategic buyer obtain conditional merger clearance for a listed stationery group. Each deal is different. What they share is that the shareholder register is being reshaped first, and the capital markets step comes afterwards.
Developments in Vietnam
 Ho Chi Minh City’s central business district.
Highlands Coffee. On 24 September Viet Thai International JSC, controlled by founder David Thai, agreed to buy an 11% stake in SF Vung Tau JSC, the operator of Highlands Coffee in Vietnam, from a subsidiary of Jollibee Foods Corporation. VnExpress International reported the price as VND2.3 trillion (US$88.4 million). The founder’s holding rises from 40% to 51% and Jollibee keeps 49%. The price implies a valuation of about US$800 million. Coverage cites an initial public offering expected in the first quarter of 2027.
Masan High-Tech Materials (MSR). The Elmet Group, a US maker of tungsten components, announced on 23 September that it will invest about US$124.75 million for 4.99% of MSR, which operates the Núi Pháo tungsten mine. Elmet will also take one board seat and sign long-term agreements for tungsten supply and for conversion services at MSR’s refining complex in Vietnam. Closing is subject to regulatory and corporate approvals. On 28 September, CafeF reported that parent company Tầm Nhìn Masan (Masan Vision) had registered to transfer up to 110.49 million MSR shares, equal to 10% of charter capital, between 1 and 30 October. Of these, 55.14 million shares are for Elmet and up to 55.36 million are for institutional investors at the same price. Masan Vision’s holding would fall from 92.45% to 82.45%. The stated purpose is to widen the shareholder base and free float ahead of a move from UPCoM to the Ho Chi Minh Stock Exchange (HOSE).
VPBank. Reuters reported on 25 September, citing four people familiar with the matter, that Sumitomo Mitsui Banking Corporation (SMBC) is in talks to raise its VPBank stake from 15% to around 20%. According to the report, price is the main point of disagreement. VPBank is seeking a premium similar to the roughly 40% SMBC paid in 2023, while SMBC has considered buying shares on the open market instead. Both banks declined to comment.
Thiên Long Group (TLG). Vietnamese media reported on 21 September that the National Competition Commission (Ủy ban Cạnh tranh Quốc gia) had cleared, with conditions, Kokuyo’s two-step acquisition of up to about 65% of the stationery maker. The first step is the purchase of the holding company that owns 46.82% of TLG, followed by a tender offer for up to 18.19% more. The conditions include annual reporting on market share and pricing, and additional research and development spending in Vietnam of at least VND3 billion a year for five years.
At the other end of the market, a state divestment showed what happens when vendor price expectations and market prices are far apart. The State Capital Investment Corporation (SCIC) had planned to auction 79.2 million shares of Seaprodex (SEA) on 29 September. The auction was cancelled because no investor registered. The starting price implied a valuation of VND13.4 trillion, or about VND107,400 per share, roughly double the market price of VND52,000 on 25 September.
Regional angle
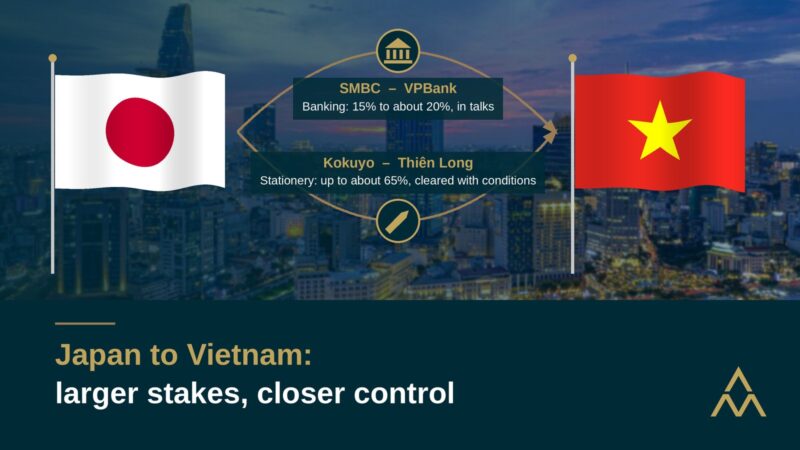 Japanese capital in this week’s deal flow: SMBC’s reported talks on a larger VPBank stake and Kokuyo’s conditionally cleared acquisition of Thiên Long.
Most of this week’s counterparties were from elsewhere in Asia or from the United States. Japanese capital appeared twice: SMBC in banking and Kokuyo in consumer manufacturing. Both are cases of a Japanese group seeking a larger stake in a Vietnamese company, or control of it. Jollibee, based in the Philippines, is doing the reverse. It is giving up control of a Vietnamese brand but keeping a 49% interest ahead of a listing. Korea’s SK Innovation took 34% of the joint venture company for the 1,500MW Quỳnh Lập LNG-to-power project in Nghệ An, alongside PV Power and Nghệ An Sugar, according to The Investor.
The Elmet–MSR transaction stands out. Bloomberg’s headline described Elmet as Pentagon-backed, and the deal links a minority equity stake to supply agreements for a critical mineral. In Alliance Mount’s view, this kind of strategic investment has been more common in resource-rich economies than in Vietnam’s recent deal history.
Across Southeast Asia, DealStreetAsia’s weekly review described the planned IPO of GCash in the Philippines as a test case for exits by private equity-backed companies. Separately, ASEAN and Hong Kong, China signed a protocol on 20 September updating their investment agreement. It is relevant to investors who hold Vietnamese assets through Hong Kong entities.
Implications for investors and companies
The following reflects Alliance Mount’s reading of the week’s developments. It is not investment advice.
Pre-listing ownership is becoming its own phase of work. In the Highlands Coffee and MSR cases, control and free float were settled before any listing. From Alliance Mount’s perspective, a market upgrade makes listing a more credible option, and owners are responding by deciding who holds control and how much stock will be available before they approach investors. For founders and parent companies considering a 2027 listing, it seems reasonable to expect shareholder agreements, tag-along and drag-along rights, and free-float plans to receive more scrutiny, and earlier, than in past cycles.
Strategic minority stakes increasingly come with commercial terms. Elmet’s investment combines equity, a board seat and supply contracts. Kokuyo’s clearance comes with commitments on research spending and reporting. Buyers are paying for access and influence, and regulators are asking for undertakings in return. As a result, deal value increasingly depends on the commercial agreements and regulatory conditions as well as on the share price.
Price discovery is becoming more disciplined. The cancelled Seaprodex auction and the reported valuation gap between SMBC and VPBank show that premiums are harder to obtain where market prices are readily available. Sellers of listed or soon-to-be-listed stakes may need to justify any premium with control rights, strategic fit or synergies. Alliance Mount’s view is that this is healthy for the market over time, even if it slows some transactions.
Portfolio and strategic capital are moving on different timetables. Net foreign selling in the week of the upgrade suggests that index-driven flows will come in bursts around tranche dates rather than in a steady stream. Strategic and direct investors appear less concerned with index timing. For companies planning equity raises, this points to timing the raise around the company’s own results and readiness rather than around index events.
What to watch
- 1–30 October: the MSR share transfer window and any subsequent HOSE listing application.
- Before year-end: whether SMBC and VPBank agree terms. Reuters reports that both sides intend to complete a deal this year.
- Timing not yet announced: the Kokuyo tender offer for Thiên Long shares, which will show how the approval conditions are applied in practice.
- 18 October: Decree 342/2026/ND-CP on retail licensing takes effect. It changes the economic needs test for some foreign retailers.
- Early October: national data on third-quarter GDP and nine-month foreign direct investment.
- Through Q1 2027: preparation for a Highlands Coffee IPO. FTSE Russell’s next inclusion tranche is scheduled for March 2027.
Alliance Mount will continue to follow how ownership changes ahead of listings affect the structure and pricing of transactions in Vietnam.